Key Takeaways
- The cost of education you pursue in order to become a licensed therapist is not tax deductible
- Once you’re a licensed therapist, continuing education that maintains or improves skills you use in your current work is generally deductible as a business expense
- Student loan interest is a separate, personal deduction: up to the lesser of $2,500 or the interest you actually paid, and it phases out at higher incomes
- You generally can’t claim the same education expense as both a deduction and an education credit
The education expense deduction for therapists may be able to lower your tax bill, provided you qualify for it.
Not all education expenses are treated the same way by the IRS, and claiming a deduction you don’t qualify for could lead to penalties.
Before you claim the education expense deduction for your therapy practice, here’s everything you need to know.
{{resource}}
What is the education expense deduction?
If you’re self-employed, the education expense deduction allows you to claim on your tax return the cost of professional education in your field.
“In your field” is a key term here. Surfing lessons, cooking classes, or your weekly novel-writing workshop don’t qualify.
What’s more, if you decide you’d rather be an electrician than a therapist, you can’t claim the cost of night classes at the local trades school on your tax return. All education you deduct must be relevant to your current field. The IRS explicitly states that you can’t claim the cost of getting an education in order to enter a new field of work.
The litmus test is whether the education you’re paying for “maintains or improves skills needed in your present work” as a therapist. That’s the IRS’s own language. If the answer is “yes,” there’s a good chance you qualify for the deduction.
Education that the law requires you to complete to keep your present status or job also qualifies, which is why courses you take to meet ongoing license renewal requirements generally count.
With one important caveat:
The education expense deduction does not cover the cost of meeting the minimum requirements to practice in your field.
For instance, to be licensed as a professional counselor in California, you need a master’s degree in counseling or psychotherapy. The cost of getting that master’s degree is not tax deductible.
Whatever additional therapist education you undertake after meeting the minimum requirements to practice is likely to qualify as tax deductible. This includes:
- Professional conferences
- Clinical trainings
- Seminars and workshops
- Online courses
The IRS also excludes education that is part of a program that will qualify you for a new trade or business, even if the coursework would otherwise sharpen your skills. If you’re self-employed, you claim qualifying education costs on Schedule C (Form 1040).
Is continuing education tax deductible?
Generally, yes. Continuing education is one of the many tax deductions for therapists. Once you’re licensed, the cost of continuing education is generally fully deductible as a business expense, as long as it maintains or improves skills you use in your current practice. The one exception is meals: if you travel for a course, meals are still only 50% deductible.
That includes both classes, seminars, and workshops you pay for in order to meet ongoing licensing requirements as a therapist, and education you pursue above and beyond those requirements.
You’re in good company if you’re planning to invest in your skills. In Heard’s 2026 Financial State of Private Practice Report, 24.6% of therapists surveyed said they plan to invest in continuing education or clinical training in 2026 (n=1,595).
Example 1: Required and optional CE in the same year
Say you pay $2,000 to meet the continuing education requirements for your license, and then, in the same year, an additional $600 for a workshop that isn’t required. Both maintain or improve skills you use in your practice, so you can generally deduct the full amount: $2,000 + $600 = $2,600. If you’re a sole proprietor, that $2,600 goes on Schedule C and reduces your business profit by the same amount.
Example 2: A trauma training with travel
Say you’re a licensed therapist who attends a three-day trauma training in another city, and you chose the trip for the training itself. Your costs are:
- Registration: $1,200
- Round-trip flight: $350
- Hotel (3 nights at $200): $600
- Meals (3 days at $50 = $150), deductible at 50%: $75
Total deduction: $1,200 + $350 + $600 + $75 = $2,225.
If you tacked on a long personal vacation, the IRS looks at how much time went to personal activities versus the training. A mainly personal trip can limit the deduction to lodging and meals on the days you attend the training. Keep your agenda and receipts, and ask your accountant if the line is blurry.
Example 3: A licensure-related course
Say you’re still working toward your license and you pay $1,500 for a course your state requires to qualify for it. That’s part of meeting the minimum requirements to practice, so it’s generally not deductible.
Two years later, now fully licensed, you pay $400 for an ethics course required to renew your license and $350 for a clinical workshop. Both generally qualify: $400 + $350 = $750.
What counts as a “minimum requirement” can depend on your state and your situation. These examples are illustrations, not tax advice, so check with an accountant before you claim anything.
What expenses does the education expense deduction cover for therapists?
Most expenses you incur in the process of receiving qualified continuing education as a therapist are tax deductible.
That includes the cost of:
- Tuition, books, and supplies
- Other expenses (hiring tutors, typists, or researchers)
- Travel expenses (sometimes)
Travel has stricter rules. Per IRS Publication 970, you can generally deduct travel, lodging, and meals for an overnight trip taken mainly to get qualifying work-related education (with meals limited to 50%). If the trip is mainly personal, only your lodging and meals for the days you attend the educational activities may qualify. Whether a trip is mainly personal or mainly educational depends on the facts and circumstances, including how much time you spend on each. Local transportation, like car mileage or transit to a course, may also qualify. There’s some gray area here, so consult with an accountant before trying to claim these expenses.
The IRS recognizes that it isn’t always easy to determine whether costs associated with education qualify for the education expense deduction. They provide an automated interview to help you figure out whether the expenses you want to claim are valid.
Are student loan payments tax deductible for therapists?
To put it briefly: No. You cannot deduct your student loan payments on your tax return.
So long as getting your post-secondary degree or degrees was a necessary part of meeting the minimum requirements to practice as a therapist, the cost of tuition does not qualify for the education expense deduction.
Also, in effect, you’re paying for the cost of education expenses you incurred before you were ever a self-employed therapist, eg. before you were able to claim education as a professional expense in the first place. It’s a catch-22.
It’s a situation many therapists share. In Heard’s 2026 Financial State of Private Practice Report, 53.6% of therapists surveyed carry student loan debt, and 20% owe more than $100,000 (n=1,671).
However, if you were hoping to write off the cost of student loans on your tax return, there is a very thin silver lining: You might be able to write off interest payments on your loan.
How therapists can write off student loan interest payments
If you paid $600 or more in interest on a qualified student loan during the year, your lender is required to send you a Form 1098-E. It lists the total interest you paid. The $600 is only the point at which lenders have to send the form. If you paid less, you may not get one, but you can generally still deduct the interest you actually paid.
You can write that amount off as an adjustment to your adjusted gross income (AGI) on your personal tax return.
The deduction is the lesser of $2,500 or the interest you actually paid during the year, and it phases out as your income rises. It’s based on your MAGI (modified AGI, which is your AGI with some deductions factored back in). For 2026, the deduction is reduced if your MAGI is between $85,000 and $100,000 ($175,000 and $205,000 if you file a joint return), and you can’t claim it at $100,000 or more ($205,000 or more for joint filers). You also can’t claim it if you file as married filing separately. The IRS updates these limits over time, so check the current year’s figures on IRS.gov or with your accountant.
This isn’t a business expense deduction. It’s an above-the-line deduction on your personal return. But it’s better than nothing.
{{resource}}
Can therapists deduct the cost of training in new types of therapy?
You know already that you can’t deduct the cost of training to enter a field different from therapy. But what about education outside your main focus as a therapist?
For example, say you run your own practice in California. You already have a master’s degree in counseling, allowing you to qualify as a professional counselor. But you decide to pursue a second degree, a master’s degree in marriage and family therapy, so you can become a Licensed Marriage and Family Therapist (LMFT).
Can you deduct the expense on your tax return?
This one is a gray area, and you shouldn’t assume the answer is “yes.” If you plan to remain in business as a self-employed therapist after receiving your new certification, you could argue that you’re not changing fields or starting a new business, just expanding the scope of clients you see.
On the other hand, you could argue that marriage and family counseling is a different field under the umbrella of therapy as a whole, and the degree you’re pursuing is allowing you to meet the minimum requirements to practice in that field—meaning it doesn’t qualify for the deduction.
Unfortunately, this is another one of those dreaded gray areas when it comes to taxes. Different states have different requirements for therapists to practice, and your personal situation comes with its own variables—whether you plan to remain in business as you are or launch a new, expanded practice, for instance.
The answer here is, “Ask your accountant”—or, if you use Heard, use in-app messaging to contact your accounting and bookkeeping team.
Can therapists deduct the cost of clinical supervision?
If you need to pay for clinical supervision in the course of getting your post-secondary degree so you can be licensed as a therapist, the cost is not tax deductible.
It’s part of the cost of meeting minimum requirements to practice in your field.
If you have to pay for supervision for other continuing education—for instance, to qualify for additional licenses as a therapist, as in the example above—the cost of supervision is only deductible if all the other expenses you’re incurring are also deductible.
With that said, if you’re licensed and you seek professional consultation from another licensed therapist, that cost would be tax deductible.
Consult with an accountant if you’re unsure.
Education credits vs. the business deduction
The business deduction isn’t the only education tax break out there. Two federal education credits, the Lifetime Learning Credit and the American Opportunity Credit, may also come up when you’re paying for courses. The key rule: the IRS says you generally can’t claim more than one benefit for the same education expense. You can claim different benefits only if each one uses different expenses.
For a licensed therapist taking continuing education, the Lifetime Learning Credit is the more relevant of the two. It covers courses taken to acquire or improve job skills, with no degree required. The American Opportunity Credit is aimed at students pursuing a degree or credential in their first four years of postsecondary education, so it usually won’t apply to CE.
Business deduction vs. education credits at a glance
| What to compare | Business deduction | Lifetime Learning Credit | American Opportunity Credit |
|---|---|---|---|
| What it covers | Education that maintains or improves skills needed in your present work (tuition, books, supplies, and some travel) | Courses taken to acquire or improve job skills. You don’t need to be pursuing a degree | Education for a student pursuing a degree or other recognized education credential |
| Limit | No set dollar cap. Reduces your business profit by the qualifying amount (meals at 50%) | Up to $2,000 per tax return (20% of the first $10,000 of qualified expenses) | Up to $2,500 per eligible student (100% of the first $2,000 plus 25% of the next $2,000) |
| Who qualifies | Self-employed therapists. Excludes education that meets minimum requirements or leads to a new trade or business | Income-limited. 2026 MAGI phase-out: $80,000 to $90,000 single, $160,000 to $180,000 joint | Income-limited. Same 2026 phase-out as the Lifetime Learning Credit. Generally only for the first four years of postsecondary education. Can’t be claimed if married filing separately |
| Typical fit for CE | Usually the main route for licensed therapists | Possible in some cases. Ask your accountant | Usually not, since it targets degree programs |
Credit income limits above are for tax year 2026. The IRS adjusts them over time, so confirm the current figures on IRS.gov. Both credits also have their own rules about where the education is provided and who can claim them. Because the business deduction has no income limit, it’s often the simpler route for self-employed therapists, but your accountant can tell you which makes sense for your return.
How to claim the education expense deduction
You claim the education expense deduction as a business expense, and where it goes depends on how your practice is set up. Which form you use varies depending on your business structure.
Where to claim the education expense deduction
| Business structure | Where you claim it |
|---|---|
| Sole proprietor | Schedule C (Form 1040) |
| Single-member LLC (taxed as a sole proprietorship) | Schedule C (Form 1040) |
| Partnership, or multi-member LLC taxed as a partnership | The partnership’s return (Form 1065). Ask your accountant how it’s handled for you as a partner |
| S corp (including a single-member LLC taxed as an S corp) | Form 1120-S. S corp owners are generally treated as employees of the company, so education costs are typically reimbursed by the S corp (for example, through an accountable plan) rather than claimed on Schedule C. Confirm with your accountant |
—
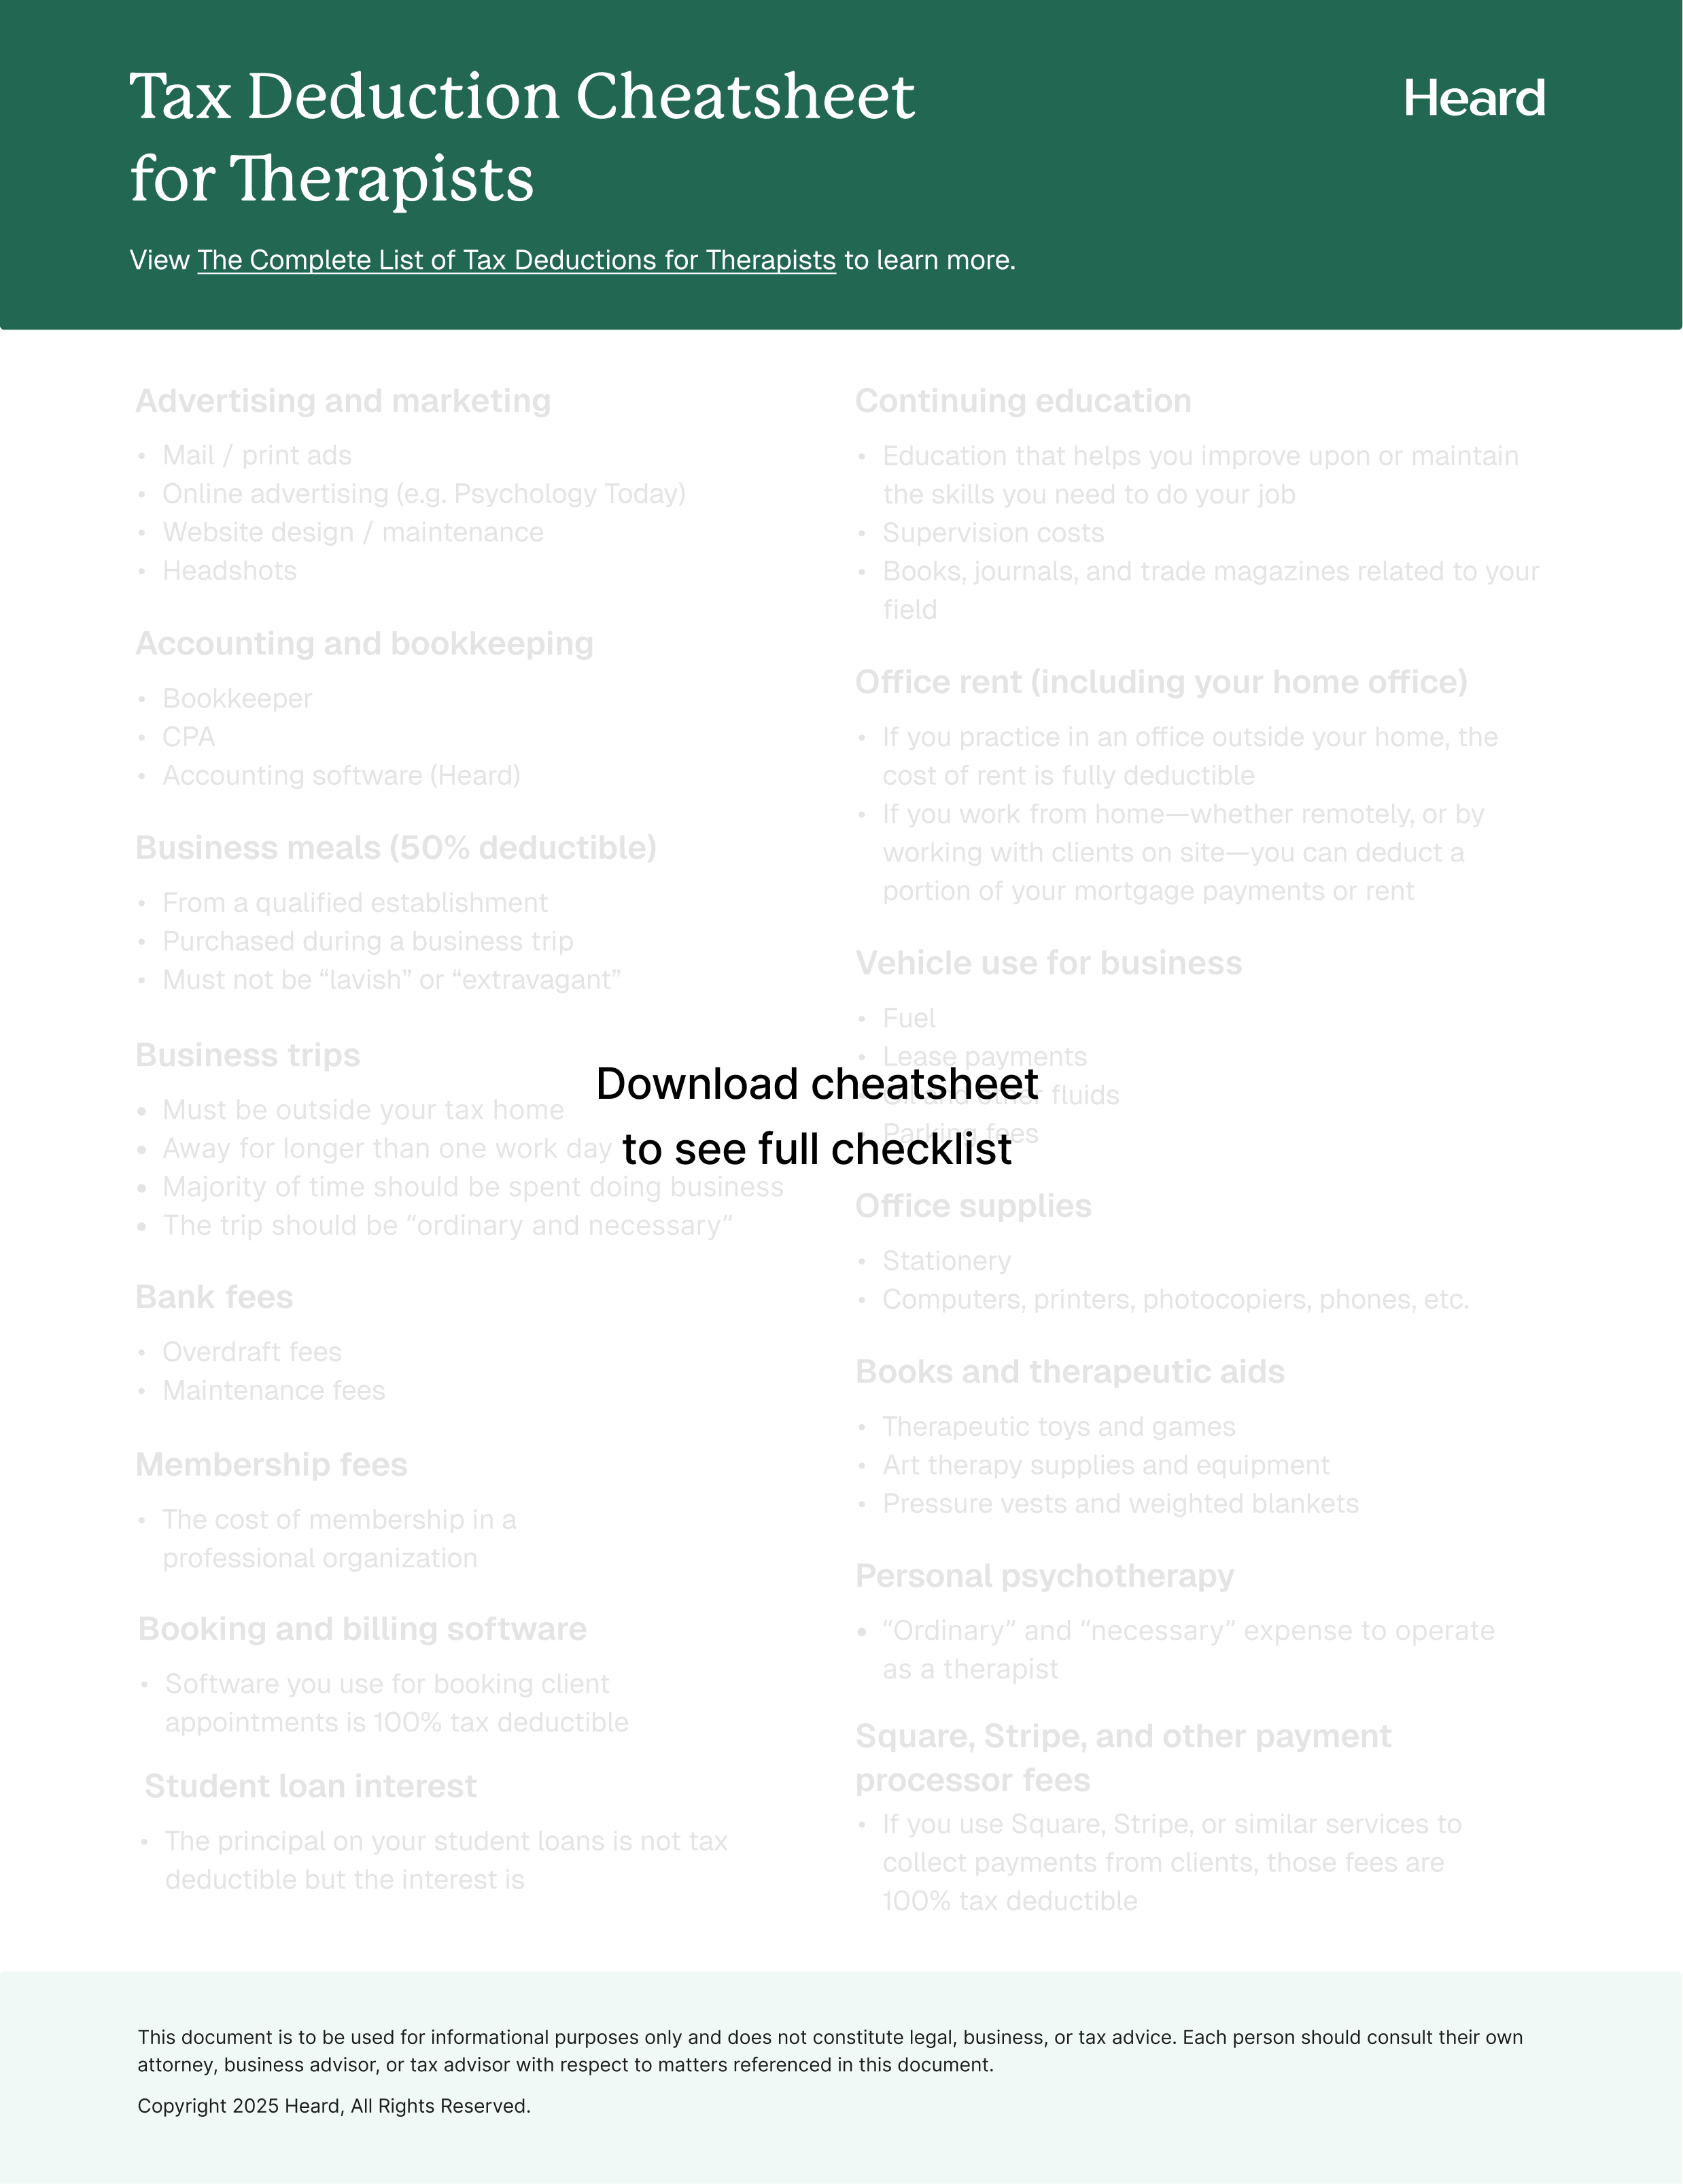
Even if you don’t qualify for the education expense deduction, there are plenty of other deductible expenses that help reduce your therapy practice’s tax burden. Check out our complete list of tax deductions for therapists.
Summary
- Continuing education is generally a tax-deductible business expense once you’re a licensed therapist, as long as it maintains or improves skills you use in your current work (meals are still 50% deductible)
- The cost of education you undertake in order to qualify for your license is not tax deductible
- Student loan interest is an above-the-line personal deduction of up to the lesser of $2,500 or the interest you actually paid, and it phases out at higher incomes (for 2026, between $85,000 and $100,000 of MAGI for single filers). A lender only has to send Form 1098-E at $600 or more
- Besides tuition, other expenses connected with continuing education, such as books and supplies, may also be tax deductible, and travel has stricter rules
- Education you undertake in order to enter a field different from psychotherapy is not tax deductible
- Education to qualify for a new license in addition to your current one may or may not be tax deductible, so consult with an accountant
- You generally can’t claim the same expense as both a deduction and an education credit
- As with all tax deductions, keep clear, organized records of all your deductible expenses
Visit our Therapist Tax Center and Tax Deductions for Therapists Hub for everything you need to know about taxes as a practice owner. If you're just starting out, here's everything you need to know about How to Start a Private Practice as a Therapist.
This post is to be used for informational purposes only and does not constitute legal, business, or tax advice. Each person should consult their own attorney, business advisor, or tax advisor with respect to matters referenced in this post.
Bryce Warnes is a West Coast writer specializing in small business finances.
{{cta}}
Manage your bookkeeping, taxes, and payroll—all in one place.

Discover more. Get our newsletter.
Get free articles, guides, and tools developed by our experts to help you understand and manage your private practice finances.